Machine Learning in Finance
This two-day course gives finance professionals a practical, end-to-end introduction to machine learning for market prediction. Participants learn how to prepare data, build leak-free features, train time-series-aware models, evaluate them properly, and convert model outputs into simple trading signals and backtests.
Recommend to a Colleague- Date:
- Please contact us
- Venue:
- Cliftons Singapore - The Finexis Building
- Fee:
This course is also available in London Time Zone and New York Time Zone
- Portfolio managers
- Traders
- Analysts and quants
- Risk and model-validation staff
- Anyone looking to apply ML in a practical investment context
- Frame ML problems correctly for financial data
- Build clean features and targets without leakage
- Train and compare baseline and tree-based models using temporal CV
- Use AutoML as a benchmark
- Explain model drivers with SHAP
- Turn predictions into positions and run simple backtests
- Basic Python
- Familiarity with financial markets and return data
- All code and templates provided; no ML background required
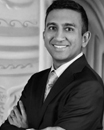
Mayank Agrawal Mayank Agrawal is a financial technology and AI specialist with more than 20 years of experience developing and deploying AI-driven solutions across financial markets. His expertise spans artificial intelligence and machine learning, systematic trading, quantitative investment strategies, risk analytics, and cloud-based financial platforms.
Mayank was the Founder and CTO of IntelliBonds, where he developed AI-powered investment strategies and a portfolio optimisation framework using advanced neural networks and cloud technologies. He has also held senior technology and quantitative roles at Citi, Bloomberg, and other global financial institutions, working on projects spanning real-time risk analytics, algorithmic trading, and AI-driven credit rating prediction.
His expertise includes AI/ML model development, systematic trading strategies, quantitative finance, and the application of advanced technology to investment and risk management.
Mayank holds an Executive MBA in Strategy and Finance from London Business School and a Master’s degree in Computer Science from Banaras Hindu University.
Request
a Brochure with full details for Machine Learning in Finance
Foundations & Strong Baselines
Data → Features → Targets
Theory
- Problem framing: regression vs classification vs ranking; target definitions that survive costs
- Data hygiene for finance: calendars, mixed frequencies, forward-fill rules, leakage traps
- Feature playbook: returns/log-returns, lags, rolling stats/z-scores, momentum/carry/spreads
- Time-aware splits: temporal CV vs random; baseline benchmarks
Practical
- Build a leak-free feature set; create 5-day return (regression) + up/down (classification) targets
- Export a clean training dataframe + quick EDA plots
Supervised ML for Tabular Time Series
Theory
- Models: Linear/Logistic (with regularization), Random Forest, Gradient Boosting, XGBoost/LightGBM
- Metrics: RMSE/MAE, PR-AUC vs ROC-AUC (imbalance), calibration, regime stability checks
- Sensible tuning: early stopping, simple grids; when to keep it simple
Practical
- Train ridge/elastic net vs LightGBM using temporal CV helpers
- Compare performance + calibration; record a 1-page “model card”
Robustness, AutoML & From Signals to Trades
Walk-Forward, Robustness & AutoML Lab
Theory
- Walk-forward validation, gap splits, regime slicing; drift checks
- Quantile regression (pinball loss) vs probability forecasts; when each helps
Practical
- Run a lightweight AutoML pass (e.g., scikit-learn-compatible AutoML) on the Session-1 dataset with time-aware CV
- Compare AutoML’s top model vs your manual LightGBM from Day 1 (metrics, stability, training time)
- Optional: quick quantile regression run to estimate upside/downside bands
Explainability → Policy Rules → Simple Backtest
Theory
- Explainability for PMs/validators: SHAP (global/local), permutation importance, sanity checks
- From predictions to trades: thresholds, confidence-based sizing, smoothing, turnover controls
- Backtest basics: costs, slippage, drawdown, turnover; common pitfalls/leakage
Practical
- SHAP on best model; verify key drivers + sign consistency
- Convert scores to positions (calibrated threshold + size by confidence / quantile bands)
- Run vectorized daily backtest; report equity curve, IR, drawdown, turnover sensitivity to costs
Course Details
This course is also available in London Time Zone and New York Time Zone
- To run this course at your organisation, contact us.
Call now for more information on this course or to book:
Asia Pacific +65 3159 3707
You may also be interested in...
London Financial Studies is registered with GARP as an Approved Provider of Continuing Professional Development (CPD) credits.