Machine Learning in Finance
This two-day course gives finance professionals a practical introduction to modern machine learning, from framing financial problems and building robust predictive models to deep learning, alternative data and deployment. Participants use OpenAI Codex throughout as an AI development assistant to help build, debug and improve models. The emphasis is on applying ML to real financial use cases and leaving with the skills to develop, validate, deploy and monitor ML workflows in their own workspace.
Recommend to a ColleagueThis course is also available in London Time Zone and New York Time Zone
- Portfolio managers, traders and investment analysts who want to use ML in investment workflows.
- Quants, developers and data professionals working with financial data.
- Analysts and quants
- Risk, model-validation and finance professionals who need to understand modern ML methods.
- Tech-savvy finance professionals who want to build practical ML solutions rather than only study theory.
- Frame real financial problems as machine-learning tasks.
- Build and compare traditional ML and deep-learning models.
- Use structured and unstructured data, including financial text.
- Validate models correctly for financial time series and understand model behaviour.
- Convert predictions into usable financial decisions or signals.
- Use Codex to accelerate ML development and debugging.
- Build, deploy and monitor an end-to-end ML workflow in their workspace.
- Working knowledge of financial markets and common financial data.
- Basic Python familiarity is helpful, but participants do not need to be expert programmers.
- No prior machine-learning or deep-learning experience is required.
- All code, datasets and templates used in the practical sessions are provided.
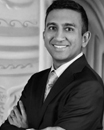
Mayank Agrawal Mayank Agrawal is a financial technology and AI specialist with more than 20 years of experience developing and deploying AI-driven solutions across financial markets. His expertise spans artificial intelligence and machine learning, systematic trading, quantitative investment strategies, risk analytics, and cloud-based financial platforms.
Mayank was the Founder and CTO of IntelliBonds, where he developed AI-powered investment strategies and a portfolio optimisation framework using advanced neural networks and cloud technologies. He has also held senior technology and quantitative roles at Citi, Bloomberg, and other global financial institutions, working on projects spanning real-time risk analytics, algorithmic trading, and AI-driven credit rating prediction.
His expertise includes AI/ML model development, systematic trading strategies, quantitative finance, and the application of advanced technology to investment and risk management.
Mayank holds an Executive MBA in Strategy and Finance from London Business School and a Master’s degree in Computer Science from Banaras Hindu University.
Request
a Brochure with full details for Machine Learning in Finance
Solving Financial Problems with Modern ML
Session 1: From Financial Problem to ML Solution — Theory
Focus: How to frame financial questions correctly and choose an appropriate modelling approach.
- Use cases: return forecasting, classification, ranking, volatility/risk prediction and regime detection.
- Financial ML challenges: low signal-to-noise, non-stationarity, leakage and changing regimes.
- Feature engineering for market and macro data.
- Model choices: linear models, Random Forest, XGBoost/LightGBM/CatBoost.
- Time-aware validation and suitable statistical and financial metrics.
Session 2: Build a Financial Prediction Model with Codex — Practical
Focus: Build a complete supervised ML workflow using financial data.
- Prepare leak-free features and prediction targets.
- Build a baseline model and a gradient-boosted model.
- Run time-aware cross-validation and compare model performance.
- Use Codex to assist with coding, debugging, documentation and iteration.
Practical output: A reusable financial ML training pipeline.
Session 3: Deep Learning for Financial Time Series — Theory
Focus: Understand when deep learning can add value beyond traditional ML.
- Neural-network fundamentals and overfitting in financial data.
- Sequence models: LSTM, TCN and Transformers.
- Attention, multi-horizon and probabilistic forecasting.
- When deep learning is useful—and when simpler models are preferable.
Session 4: Build and Compare a Deep-Learning Model — Practical
Focus: Train a sequence model and test whether additional complexity improves out-of-sample results.
- Prepare sequential training data.
- Train an LSTM, TCN or Transformer model.
- Compare performance with the Day 1 gradient-boosted model.
- Use Codex to modify architecture, parameters and diagnostics.
Practical output: A working deep-learning model with a disciplined benchmark comparison.
From Alternative Data to Deployable ML Systems
Session 5: Alternative Data, NLP and Robust Models — Theory
Focus: Learn how to extract signal from unstructured data and assess whether models are genuinely robust.
- Financial text: news, filings, earnings calls and central-bank communication.
- Embeddings and modern text representations.
- Combining text and numerical market features.
- Walk-forward validation, regime analysis, drift and purging/embargo.
- Explainability with feature importance, SHAP and model diagnostics.
Session 6: Build a Multi-Source Financial Model — Practical
Focus: Combine market data and text into one predictive workflow.
- Generate text embeddings and combine them with numerical features.
- Compare market-only, text-only and combined models.
- Use SHAP to understand important drivers.
- Test robustness across time and market regimes using Codex-assisted analysis.
Practical output: A multi-source financial model with explainability and robustness checks.
Session 7: From Prediction to Decision and Production — Theory
Focus: Understand how a research model becomes a usable system in a financial workspace.
- Turn scores and probabilities into decisions, rankings, signals or positions.
- Thresholds, sizing, turnover, transaction costs and risk-adjusted evaluation.
- The ML lifecycle: data → training → validation → deployment → monitoring → retraining.
- Experiment tracking, model versioning, batch/real-time inference and drift monitoring.
- Using Codex to refactor research code, create tests, APIs, dashboards and deployment components.
Session 8: Capstone — Build and Deploy an End-to-End ML Workflow — Practical
Focus: Bring the entire course together into a workflow participants can adapt to their own workplace.
- Define a financial problem and build the data and feature pipeline.
- Train, validate and select a model.
- Convert predictions into a financial decision or signal.
- Package the model for repeatable inference.
- Deploy via a simple API, dashboard or scheduled process.
- Define monitoring and retraining rules using Codex as the development assistant.
Practical output: A reusable template for developing, deploying and monitoring ML models in the participant’s own workspace.
End-of-course capability. Participants should leave able to take a real financial problem and move through the full workflow: frame it → build the data → develop the model → validate it → deploy it → monitor it.
Course Details
This course is also available in London Time Zone and New York Time Zone
- To run this course at your organisation, contact us.
Call now for more information on this course or to book:
Asia Pacific +65 3159 3707
You may also be interested in...
London Financial Studies is registered with GARP as an Approved Provider of Continuing Professional Development (CPD) credits.