Stochastic Calculus
The use of probability theory in financial modeling can be traced back to the work on Bachelier at the beginning of last century with advanced probabilistic methods being introduced for the first time by Black, Scholes and Merton in the seventies.
Modern financial quantitative analysts make use of sophisticated mathematical concepts, such as martingales and stochastic integration, in order to describe the behavior of the markets or to derive computing methods.
This course bridges the gap between mathematical theory and financial practice by providing a hands-on approach to probability theory, Markov chains, and stochastic calculus. Participants will practice all relevant concepts through a batch of Excel based exercises and workshops.
Recommend to a Colleague- Date:
- Please contact us
- Venue:
- Manhattan - New York
- Fee:
This course is also available in London Time Zone and Singapore Time Zone
- Quantitative analysts
- Financial engineers
- Researchers
- Risk managers
- Structurers
- Market analysts and product controllers
Past participants have included: Chief investment officers, Asset Managers, Strategists, Private Banks, Relationship Managers
Delegates should have a good understanding of Elementary Probability Theory, Calculus and Linear Algebra (covered in Maths Refresher).
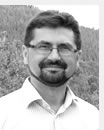
Dan Crisan is Professor of Mathematics at Imperial College London, specialising in stochastic analysis and its applications to engineering and finance. His research focuses on stochastic and deterministic partial differential equations, backward stochastic differential equations, nonlinear filtering, and numerical methods for stochastic systems.
He has published more than 30 research articles in international academic journals. His current work includes the development of high-order numerical algorithms and particle methods for the analysis and approximation of complex stochastic systems, with applications across mathematics, engineering, and financial modelling.
Request
a Brochure with full details for Stochastic Calculus
Probability Theory
- Random variables, independence and conditional independence. Discrete random variables: mass density, expectation and moments calculation
- Conditional discrete distributions, sums of discrete random variables
- Continuous random variables; Probability density function, cumulative probability density function; Expectation and moments calculation; Conditional distributions and conditional expectation; Functions of random variables
Examples: Normal distribution, gamma distribution, exponential distribution, Poisson distribution
Exercise: Properties of the gamma distribution and the log-normal distribution
Workshop: Multivariate normal distributions. Linear transformations. Counter-example
- Generating functions. Moment generating functions. Characteristic functions
- Convergence theorems: the strong law of large numbers, the central limit theorem
Examples: Characteristic functions of Bernoulli, binomial, exponential distributions
Exercise: Moment generating functions and characteristic functions of Poisson, normal and multivariate normal distributions
Markov Chains
- Discrete time Markov chains, the Chapman-Kolmogorov equation
- Recurrence and transience. Invariance
- Discrete martingales. Martingale representation theorem. Convergence theorems
Examples: Random walks: simple, reflected, absorbed
Workshop: Pricing European options within the Cox-Ross-Rubinstein model
- Continuous time Markov chains. Generators
- Forward/backward equations. Generating functions
Examples: The Poisson process
Exercise: Superposition of Poisson Processes. Thinning
Stochastic Calculus
- The Wiener process. Path properties. Monte Carlo simulation
- Gaussian processes. Diffusion processes
Examples: The Wiener process with drift. The Brownian Bridge
Exercise: The Geometric Brownian Motion. Properties of its distribution (moments)
- Semi-martingales. Stochastic integration
- Ito's formula. Integration by parts formula
Workshop: Multivariate normal distributions. Linear transformations. Counter-example
Examples: Characteristic functions of Bernoulli, binomial, exponential distributions
Exercises: Moment generating functions and characteristic functions of Poisson, normal and multivariate normal distributions
Stochastic Differential Equations
- Stochastic differential equations. Existence and uniqueness of solutions. Equations with explicit solutions
- The Markov property. Girsanov's theorem
Exercise: The Vasicek model. Connection with the O-U process. Mean. Variance. Covariance. Pricing zero-coupon bonds
Workshop: The Cox Ingersoll Ross Model. Connection with the O-U process. Properties of its distribution (mean variance, covariance). Pricing zero-coupon bonds
Great course with a very skilful and communicative tutor. It exceeded my expectations and strengthened my knowledge of the subject in a short time.
(Risk Manager - Banca d'Italia)
Wonderful group of people at LFS - efficient, professional and dedicated to you for the duration of your course. I was particularly impressed with the curation of a reading list available to all those that sign up for a course - something you have access to for up to a year following your course date!
(Quantitative Developer - Royal Bank of Scotland)
Very good subject knowledge and enthusiam for teaching.
(Quantitative Developer - Royal Bank of Scotland)
The LFS stochastic calculus course has enhanced my abilities in very little time. The professor transformed my abstract knowledge of the subject into a firm foundation, which I will be drawing on in my role going forward.
(Analyst - Aberdeen Asset Management)
The course provides a good overview of the basic building blocks of stochastic calculus and its applications.
(Asset Manager - ZZ Vermogensverwaltung)
I was struggling to understand the fundamental theory underpinning stochastic modelling by reading on my own and attending this course helped as the concepts were explained very well by the tutor.
(Corporate Actuary - Scor SE - UK Branch)
This was a valuable opportunity to receive advanced training from an excellent expert in the field, Professor Dan Crisan. The distinguishing aspect of this course is that it actually walks through the theory underlying stochastic differential equations.
(Risk Analyst - Investment Management)
Course Details
This course is also available in London Time Zone and Singapore Time Zone
- To run this course at your organisation, contact us.
Call now for more information on this course or to book:
Americas +1 212 710 1343
London Financial Studies is registered with GARP as an Approved Provider of Continuing Professional Development (CPD) credits.